The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Secured and unsecured loans differ mainly in whether an asset is used as security. This guide explains how that difference can affect borrowing risk, eligibility, loan costs and repayment decisions for Australian consumers and small business owners.
When comparing finance options, one of the first questions is whether the loan is secured or unsecured. The difference can affect what you may be eligible for, how the lender assesses risk, the interest rate and fees you may be offered, and what could happen if repayments are not made.
This guide explains secured and unsecured loans in Australia in general terms for consumers and small business owners. It is not personal financial advice, and the right structure will depend on your circumstances, the loan purpose, the asset involved and lender criteria.
What is a secured loan?
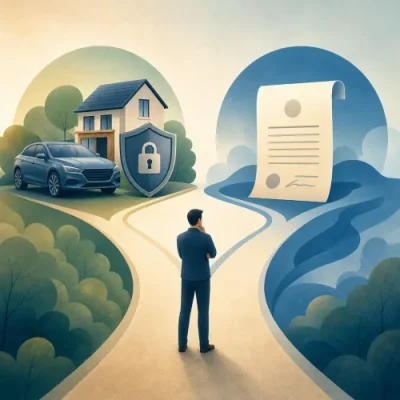
A secured loan is a loan where the borrower provides an asset as security for the debt. This asset is often called collateral or loan security. If the borrower defaults and the issue cannot be resolved, the lender may have rights to take action against the secured asset, subject to the loan contract and applicable laws.
Common examples of secured lending can include:
- car loans secured against the vehicle being purchased;
- equipment or asset finance secured against business equipment;
- home loans secured by a mortgage over property;
- some business loans secured by business assets, property, vehicles or other acceptable collateral.
Security does not remove the need to repay the loan. It gives the lender an additional form of protection if the borrower does not meet the agreed repayments.
What is an unsecured loan?
An unsecured loan does not require a specific asset to be pledged as security for that loan. The lender instead relies more heavily on factors such as income, cash flow, credit history, existing debts, expenses and overall serviceability.
Unsecured loans may be used for a range of personal or business purposes, depending on the lender and product. Examples can include some personal loans, business loans, lines of credit or overdrafts where no particular asset is offered as collateral.
Unsecured does not mean risk-free. If repayments are missed, the lender may still charge fees, report missed payments where permitted, take debt recovery action or pursue other remedies available under the contract and law.
Secured versus unsecured loan: the main differences
The key difference is the presence or absence of a specific asset offered as security. That difference can flow through to cost, eligibility and borrower risk.
| Feature |
Secured loan |
Unsecured loan |
| Loan security |
An asset is used as collateral, such as a car, equipment, property or other acceptable asset. |
No specific asset is pledged as security for the loan. |
| Lender risk |
The lender may have additional recovery options if the borrower defaults. |
The lender generally relies more on the borrower’s creditworthiness and capacity to repay. |
| Potential borrowing cost |
May have lower interest rates than comparable unsecured lending, depending on the borrower, asset and lender. |
May have higher rates than secured lending because the lender may be taking on more risk. |
| Eligibility |
May depend on both borrower assessment and whether the asset is acceptable security. |
May depend more heavily on income, cash flow, credit history, debts and serviceability. |
| Default risk |
The secured asset may be at risk if repayments are not made and the default is not resolved. |
No specific secured asset is attached, but legal recovery, credit reporting and financial consequences may still apply. |
| Common uses |
Vehicles, property, equipment, caravans, boats and some business assets. |
Personal expenses, cash flow needs, debt consolidation or business working capital, subject to lender criteria. |
How security can affect loan costs
Because secured lending gives a lender an asset to rely on if the borrower defaults, it may be priced differently from unsecured lending. In many cases, a secured loan may have a lower interest rate than a similar unsecured loan, but this is not guaranteed.
Loan costs can be affected by many factors, including:
- the borrower’s credit history and repayment conduct;
- income, employment, business revenue or cash flow;
- existing debts and living or operating expenses;
- the loan amount, loan term and repayment structure;
- the type, age, condition and value of the asset used as security;
- whether the loan is fixed or variable;
- establishment fees, monthly fees, early repayment costs and other charges.
When comparing offers, look beyond the advertised interest rate. Fees, repayment frequency, loan term and early repayment conditions can all affect the total amount paid over the life of the loan. You can use financial calculators to model repayment scenarios, but calculator results are estimates only and will depend on the inputs used.
How security can affect eligibility
Security can influence eligibility, but it does not override the need to show that the loan is affordable. Lenders usually assess whether the borrower can meet repayments based on income, expenses, liabilities and credit history.
For a secured loan, the lender may also review the proposed security. This can include whether the asset is acceptable, whether it can be valued, whether it is already financed, and whether the lender can register an interest over it. For example, a lender considering a vehicle or business equipment loan may assess the asset as well as the borrower.
For an unsecured loan, the lender has no specific asset securing the debt, so the borrower’s financial position and repayment capacity may carry more weight. This does not mean unsecured loans are easier or harder to obtain in every case. Eligibility depends on the lender’s criteria, the product, the loan purpose and the applicant’s circumstances.
If you want to understand what lenders may review before you apply, see this guide to finance eligibility assessments in Australia.
Borrowing risk: what happens if you cannot repay?
The consequences of missed repayments can be serious for both secured and unsecured loans. The specific process depends on the loan type, the contract, the lender and applicable legal requirements.
Personal Loan Repayment Calculator

Explore potential personal loan repayment scenarios with our Personal Loan Calculator. Test different borrowing amounts, interest rates and loan terms, and review estimated repayment schedules to see how varying assumptions may affect your repayments and total borrowing costs.
Risks with secured loans
With a secured loan, the asset used as security may be at risk if the borrower defaults and the issue is not resolved. Depending on the circumstances, a lender may be able to repossess or sell the asset after following required processes.
If the asset is sold and the sale proceeds do not cover the remaining loan balance, fees and recovery costs, the borrower may still owe the shortfall. This is an important point: handing back or losing the secured asset does not always end the debt.
Risks with unsecured loans
With an unsecured loan, there may be no specific asset for the lender to repossess under that loan. However, missed repayments can still lead to default fees, debt collection activity, legal action and negative credit reporting where permitted.
Unsecured lending may feel simpler because there is no asset tied to the loan, but the obligation to repay remains. Borrowers should still consider whether repayments will remain manageable if income falls, business revenue changes or unexpected expenses arise.
Personal loan security: when might each structure suit?
For consumers, secured personal lending is often linked to a specific asset, such as a car, caravan or boat. Unsecured personal loans may be used where there is no suitable asset, where the purpose is more general, or where the borrower does not want to provide a specific asset as collateral.
Potential reasons someone may consider a secured personal loan include:
- the loan is for an asset the lender is willing to accept as security;
- the borrower wants to compare whether secured pricing is more competitive;
- the borrower is comfortable with the asset being tied to the loan.
Potential reasons someone may consider an unsecured personal loan include:
- there is no suitable asset to offer as security;
- the borrower does not want a particular asset attached to the loan;
- the loan purpose is not tied to a single financed asset.
Neither option is automatically better. The trade-off is usually between cost, flexibility, eligibility and the risk of putting an asset on the line.
Business loan security: assets, guarantees and cash flow
For small business owners, security can be more complex. A business loan may be secured by equipment, vehicles, invoices, business assets, commercial property or other acceptable collateral. Some lenders may also require a director’s guarantee or personal guarantee, depending on the structure and borrower profile.
A guarantee is not the same as asset security, but it can still create serious personal obligations. If a business cannot repay, the guarantor may become responsible for the debt under the terms of the guarantee. Business owners should read loan and guarantee documents carefully and consider getting professional advice before signing.
Secured business finance may be useful where the loan is connected to an asset, such as machinery or equipment. Unsecured business finance may be considered for working capital, cash flow gaps or general business needs. In either case, lenders commonly look at revenue, profitability, bank statements, tax obligations, existing debts and the business owner’s credit profile.
For a broader overview of business finance structures, you may find Types of Business Finance in Australia and How They Work useful.
Questions to ask before choosing a secured or unsecured loan
Before applying for either type of loan, consider asking:
- What asset is being used as security? If the loan is secured, make sure you understand exactly what asset is attached to the debt.
- What happens if I miss repayments? Ask about arrears processes, hardship options, default fees and potential recovery action.
- What is the total cost of the loan? Compare interest, comparison rates where relevant, fees, charges and the impact of the loan term.
- Can I repay early? Check whether additional repayments or early payout are allowed and whether fees apply.
- Is the asset likely to hold value? Some assets depreciate, which may matter if the asset is sold before the loan is repaid.
- Will the loan purpose fit the product? Some lenders restrict how funds can be used.
- Am I comfortable with the risk? A lower rate may not be worthwhile if the security arrangement creates risk you are not prepared to accept.
How brokers and comparison services may help
A finance broker or quote comparison service may help borrowers compare secured and unsecured options across participating lenders or referral partners. The process can vary, and not every broker or comparison service works with the same lender panel.
Broker support may be useful if you are unsure which loan structure fits the purpose, whether an asset is acceptable security, or how lenders may view your application. However, a broker or referral service cannot guarantee approval, a particular rate or a specific outcome. Any loan offer will depend on lender assessment, product availability and your individual circumstances.
If you choose to seek assistance, you can review the site’s broker information to understand the general support pathway.
Final Thoughts
- A secured loan uses an asset as collateral; an unsecured loan does not attach a specific asset to the debt.
- Secured loans may offer different pricing or borrowing limits, but the secured asset may be at risk if repayments are not made.
- Unsecured loans can avoid pledging a specific asset, but missed repayments can still lead to fees, credit impacts and recovery action.
- Eligibility depends on more than security. Lenders also assess income, expenses, debts, credit history, loan purpose and serviceability.
- For business borrowers, guarantees and security arrangements should be reviewed carefully because they can create personal and business risks.
- The right structure depends on your needs, repayment capacity, risk tolerance and the lender’s criteria.
Before committing to any finance product, compare the total cost, understand the default consequences and make sure the repayments fit comfortably within your budget or business cash flow.
Published: Thursday, 5th Nov 2026
Author: Paige Estritori



No comments yet. Be the first to share your thoughts.