Finance Australia Personal Loan Repayment Calculator
Calculate repayments with our Personal Loan Calculator. Compare loan terms, view repayment schedules, and plan your personal finance with confidence.
Calculator results are estimates based on the inputs and assumptions used and are provided for general information only. They are not quotes, offers, approvals, eligibility decisions or personalised recommendations. Actual costs and repayments may differ.
Personal Loan Details:
Important!
Personal Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Personal Loan Amortisation Calculator
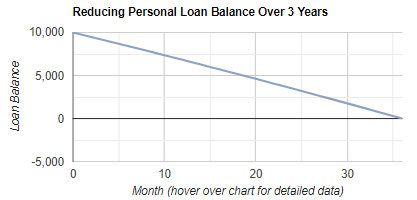
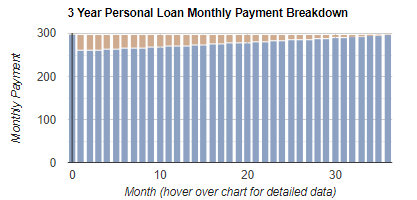
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Personal Loan Repayment Calculator
Our Personal Loan Repayment Calculator helps you estimate your ongoing loan repayments and the total cost of borrowing before you apply. By adjusting the loan amount, loan term and interest rate, you can compare scenarios and choose a repayment level that better fits your budget. It also provides an amortisation view so you can see how each repayment is split between interest and principal over time.
Important note for ASIC compliance: this calculator provides general information only and does not take into account your objectives, financial situation or needs. Results are estimates and may not include lender fees, comparison rates, commissions, insurance, redraw features, or changes to your interest rate. Always check a lender’s final quote and loan contract before deciding.
How to complete the form for the best result
1. Loan Amount Required: Enter the total amount you want to borrow in Australian dollars as a whole number (no decimals or commas). Use the amount you actually need, not the maximum you might be approved for, to avoid overpaying interest.
2. Term of Loan: Select the number of years you plan to repay the loan over. A longer term can reduce the monthly repayment, but typically increases the total interest paid over the life of the loan.
3. Interest Rate: Choose an annual interest rate for the simulation. If you have a lender quote, use that rate. If not, test a conservative range to understand best case and worst case outcomes.
4. Calculate: Click the calculate button to generate your results.
How to interpret the results
1. Repayment estimate: Treat the repayment figure as your baseline commitment. Stress-test your budget by increasing the rate or shortening the term to see if repayments remain affordable.
2. Amortisation and graphs: Review the month-by-month amortisation view and charts to understand how the balance reduces and how early repayments often include a higher interest portion, shifting toward more principal over time.
3. Compare scenarios: Re-run the calculator with different terms and rates to balance affordability (cash flow) against total interest (overall cost).
Welcome to the digital age, where online loans in Australia offer convenience and accessibility like never before. With a few clicks, financing for your next big purchase or consolidation of existing debts is at your fingertips. However, venturing into the world of online lending without a compass can leave you navigating choppy waters. - read more
Having a robust credit profile is one of the most critical factors for financial health, especially when seeking loans in Australia. Whether you're eyeing a new car, dreaming of a home or simply want to secure a personal loan for unexpected expenses, your credit score often dictates the outcome. Not only does it influence a lender's decision to offer you finance, but it also affects the interest rates you might be charged. - read more
A practical guide to the main types of business finance available in Australia, including term loans, lines of credit, overdrafts, invoice finance, equipment finance, and secured or unsecured lending. - read more
APRA’s latest banking indicators point to a lending market that is still open, but not loose. Mortgage credit continues to move through the system, yet the regulator’s focus on serviceability, risk controls and higher-risk lending means borrowers should expect applications to be examined carefully rather than waved through on headline income alone. - read more
Australia’s latest national accounts have given borrowers a fresh read on the economy: growth is continuing, but momentum remains uneven and household spending is still being tested by higher living costs. For anyone weighing up a personal loan, home loan refinance, vehicle finance or business funding, the message is less about one headline number and more about how stable income, expenses and cash flow look over the next year. - read more
Fresh lending and banking indicators are giving Australian borrowers a timely reminder: the headline interest rate is only one part of the finance decision. While some lenders have been adjusting selected offers and competition remains visible in parts of the market, arrears and repayment stress are still important signals for households and small to medium-sized businesses planning their next move. - read more
Mortgage Document: The physical contract agreement that a Mortgagee (lender) enters into with a Mortgagor (borrower) outlining the precice terms of a mortgage loan.