Finance Australia :: News
SHARE

Share this news item!

What tighter lending signals mean for new loan applications

Approval is still possible, but stronger preparation matters

What tighter lending signals mean for new loan applications?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

APRA’s latest banking indicators point to a lending market that is still open, but not loose.
Mortgage credit continues to move through the system, yet the regulator’s focus on serviceability, risk controls and higher-risk lending means borrowers should expect applications to be examined carefully rather than waved through on headline income alone.

For households, this sits alongside recent growth data showing that the economy is still expanding, but with uneven momentum. That matters because lenders do not assess a loan application in isolation. They look at income stability, existing debts, living costs, repayment history and the amount of buffer available if expenses rise or income changes.

The practical message is especially important for borrowers considering a refinance, property purchase, car loan, personal loan or debt consolidation. A lower advertised rate may look attractive, but approval and final pricing can still depend on whether the lender believes the repayments are sustainable. For many applicants, the key hurdle is no longer simply finding a product; it is demonstrating that the proposed debt fits comfortably within their broader financial position.

Small business owners should also pay attention. Even when a loan is for personal purposes, lenders may scrutinise business income, tax records, cash flow volatility and existing commitments. Where the application is for business finance, the same discipline applies: up-to-date financials, clear loan purpose, realistic forecasts and evidence of repayment capacity can make the process smoother.

Before applying, borrowers should review three areas. First, check whether income documentation is current and consistent. Second, list all existing credit commitments, including cards, buy now pay later accounts, vehicle finance and business facilities. Third, model repayments under more than one scenario, rather than relying on the most optimistic rate or term.

This does not mean borrowers should avoid finance altogether. It means finance decisions need to be made with clearer numbers and fewer assumptions. In a market where lenders remain cautious, preparation can be the difference between a rushed application and a more informed conversation about suitable options. The strongest applicants are likely to be those who can show not only that they want finance, but that they have tested how it will work in real life.

Published:Tuesday, 15th Sep 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.

Finance News

Why private credit scrutiny matters for business finance decisions
17 Nov 2026: Paige Estritori
Australia’s private credit market has moved further into regulatory focus after fresh warnings from APRA and ASIC highlighted both its growing role in business funding and the weaknesses that can emerge when lending shifts outside traditional banking channels. For small and medium-sized businesses, the issue is not that non-bank finance is automatically unsuitable. - read more
RBA rate rise puts repayment buffers back in focus
10 Nov 2026: Paige Estritori
The Reserve Bank of Australia’s November decision to lift the cash rate target to 4.85 per cent has reset the finance planning conversation for households and small businesses. After months of watching inflation, wages, fuel costs and lender settings, borrowers now have a clearer signal that higher repayment pressure may persist for longer than many had hoped. - read more
Why stronger business lending is not a simple green light for SMEs
03 Nov 2026: Paige Estritori
Westpac’s latest full-year result has added a useful signal for Australian business borrowers: credit demand remains strong even as interest rates and operating costs keep pressure on cash flow. The bank reported on 2 November 2026 that its overall lending grew over the year, with business lending rising more quickly than many household-facing categories, reinforcing the sense that firms are still using finance to invest, refinance and manage working capital. - read more


Finance Articles

How to Improve Your Chances of Getting a Business Loan Approved
Welcome, Australian entrepreneurs and business owners! Whether you're just setting down the foundation of a startup or steering a well-established enterprise, access to capital remains a critical ingredient for business growth and survival. In the bustling economy of Australia, a well-structured business loan can be the catalyst that propels your business forward, aiding in expansion, the acquisition of new equipment, or simply ensuring smooth operational cash flow during lean periods. - read more
The Role of Business Insurance in Protecting Your Australian Enterprise
Starting and running a business in Australia can be an exhilarating experience, full of opportunities for growth and success. However, it also comes with its fair share of risks and uncertainties. From unexpected natural disasters to potential legal disputes, the threats to the sustainability of a business are ever-present. This is where business insurance becomes pivotal as a protective tool for Australian enterprises. It provides the much-needed safety net to help businesses mitigate potential losses and continue operations with confidence. - read more
How Finance Brokers and Quote Comparisons Work in Australia
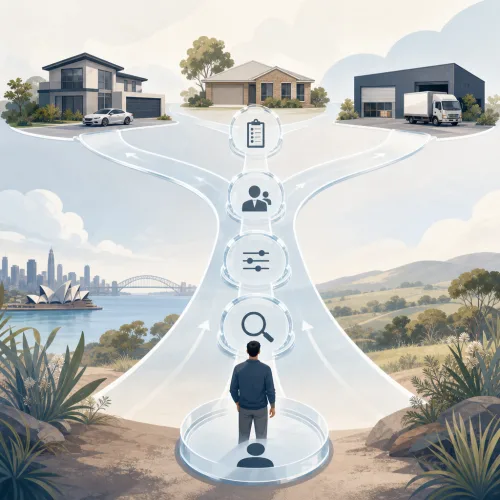
Finance brokers and quote comparison services can help Australian borrowers explore personal, home, vehicle or business finance options, but they do not all work the same way. This guide explains the typical process, what brokers may do, how referral networks and lender panels operate, and what to check before proceeding. - read more

Personal Loan Repayment Calculator

Personal Loan Repayment Calculator

The Great Australian Side-Hustle

The Great Australian Side-Hustle

Finance Australia's Weekly Money and Business News

Finance Australia's Weekly Money and Business News

Stay informed with MoneyTips

Get practical financial information, news, guides and resources.


Knowledgebase
Compound Interest:
Interest calculated on the initial principal, which also includes all accumulated interest from previous periods.