Explore potential mortgage repayment scenarios with our Home Loan Repayment Calculator. Adjust loan amounts, interest rates and repayment terms, and view detailed amortisation charts to see how different scenarios may affect your repayments, interest costs and outstanding loan balance over time.
Calculator results are estimates based on the inputs and assumptions used and are provided for general information only. They are not quotes, offers, approvals, eligibility decisions or personalised recommendations. Actual costs and repayments may differ.
Home Loan Details:
Important!
Home Loan Interest Rates differ from lender to lender and will depend on your individual circumstances (credit history, employment status, age, etc.).
Home Loan Amortisation Calculator
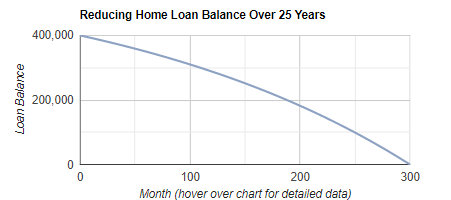
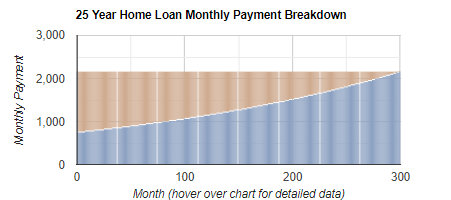
The following amortisation graphs detail month-by-month data on the progress of the proposed loan. The first chart below examines the reducing loan balance over the course of the finance contract term. The second graph illustrates the portion of each monthly repayment allocated to payment of interest vs principal reduction.
How to use our Home Loan Repayment Calculator
Our Home Loan Repayment Calculator helps you estimate your mortgage repayments in Australia and understand how a loan may reduce over time. It is useful for budgeting, comparing loan terms, and visualising an amortisation schedule (how each repayment is split between interest and principal). The calculator is designed for planning only and works best when you enter realistic assumptions.
Important information: Results are estimates only and do not constitute a quote. Interest rates and loan features vary by lender and may change. This information is general and does not take into account your objectives, financial situation or needs. Consider whether it is appropriate for you and seek professional advice if required.
How to complete the calculator fields (in order):
1. Purchase Price: Enter the property purchase price. If you expect to borrow extra for costs, you may choose to include amounts such as stamp duty, insurance, and other buying costs in this figure so your estimate reflects your likely loan size. Enter whole numbers only (no dots or commas).
2. Deposit or Equity Value: Enter your cash deposit or usable equity from another property (if applicable). A higher deposit generally reduces the loan amount and can lower repayments. Enter whole numbers only (no dots or commas).
3. Term of Loan (years): Select the number of years to repay the loan. Longer terms usually reduce repayments but increase total interest paid over the life of the loan.
4. Interest Rate (% per annum): Select an interest rate for the simulation. Use a realistic rate and consider testing higher rates to understand “rate rise” risk.
5. Calculate: Click calculate to generate your results.
How to interpret the results:
1. Repayment estimate: Use this as a starting point for affordability checks, remembering real loans may include fees and different features.
2. Amortisation charts: Review the loan balance chart to see how your balance falls over time, and the interest versus principal chart to understand how early repayments are typically interest-heavy, then shift toward principal reduction later.
3. Compare scenarios: Adjust the term, deposit/equity, or interest rate and recalculate to compare loan terms and see how changes affect repayments and total interest over time.
Welcome, Australian entrepreneurs and business owners! Whether you're just setting down the foundation of a startup or steering a well-established enterprise, access to capital remains a critical ingredient for business growth and survival. In the bustling economy of Australia, a well-structured business loan can be the catalyst that propels your business forward, aiding in expansion, the acquisition of new equipment, or simply ensuring smooth operational cash flow during lean periods. - read more
Starting and running a business in Australia can be an exhilarating experience, full of opportunities for growth and success. However, it also comes with its fair share of risks and uncertainties. From unexpected natural disasters to potential legal disputes, the threats to the sustainability of a business are ever-present. This is where business insurance becomes pivotal as a protective tool for Australian enterprises. It provides the much-needed safety net to help businesses mitigate potential losses and continue operations with confidence. - read more
Welcome to the world of savvy home financing! Whether you’re a first-time homebuyer or seasoned investor, navigating the ocean of home loan options can be daunting. In this digital era, one tool stands out for its effectiveness in simplifying this journey: the online home loan calculator. - read more
Westpac’s latest full-year result has added a useful signal for Australian business borrowers: credit demand remains strong even as interest rates and operating costs keep pressure on cash flow. The bank reported on 2 November 2026 that its overall lending grew over the year, with business lending rising more quickly than many household-facing categories, reinforcing the sense that firms are still using finance to invest, refinance and manage working capital. - read more
APRA’s latest banking indicators point to a lending market that is still open, but not loose. Mortgage credit continues to move through the system, yet the regulator’s focus on serviceability, risk controls and higher-risk lending means borrowers should expect applications to be examined carefully rather than waved through on headline income alone. - read more
Australia’s latest national accounts have given borrowers a fresh read on the economy: growth is continuing, but momentum remains uneven and household spending is still being tested by higher living costs. For anyone weighing up a personal loan, home loan refinance, vehicle finance or business funding, the message is less about one headline number and more about how stable income, expenses and cash flow look over the next year. - read more
Equity: The amount of (or that portion of) an asset actually owned. Equity is the difference between the market value and the current amount of money still owing on the loan. This is also referred to as the owner’s interest.