Finance Australia :: News
SHARE

Share this news item!

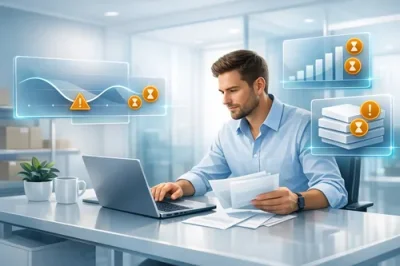
Why late invoices are becoming a finance risk for small businesses

Long payment terms can quietly shift borrowing pressure onto suppliers

Why late invoices are becoming a finance risk for small businesses?w=400

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

Australia’s small business sector is facing a sharper cash flow test as long payment terms collide with higher operating costs, stricter compliance obligations and rising insolvency numbers.
The latest concern is not simply that customers are paying late.
It is that many small firms are effectively being asked to provide interest-free credit to larger customers while still meeting wages, rent, insurance, tax and supplier bills on time.

Recent ASIC insolvency data has added weight to the issue. Company external administrations and controller appointments for the 2025–26 financial year were substantially higher than pre-pandemic levels, with very small employers making up the overwhelming share of affected companies. For owners already managing tight margins, one large unpaid invoice can quickly become a funding problem rather than an administrative inconvenience.

The practical issue is straightforward. When a business completes work or supplies stock before being paid, it often carries the cost of labour, materials, GST, software, transport and overheads upfront. If payment stretches to 45 or 60 days, that gap may be covered by an overdraft, credit card, personal savings or a loan secured against household assets. In other words, the supplier is taking on working-capital risk that would normally sit with a lender.

This matters even more from July 2026, with payday super requiring employers to align superannuation contributions more closely with wage cycles. The policy aim is sound, but it reduces the room for businesses to rely on quarterly timing differences. Combined with higher insurance, energy and compliance costs, owners have less flexibility to absorb customer delays.

For small and medium-sized businesses, the response should be both commercial and financial. Commercially, owners can review payment terms, request deposits, use progress payments, tighten debtor follow-up and decide which customers should receive credit. Financially, they should understand their short-term funding options before pressure becomes urgent. Comparing business finance options early can help owners assess whether an overdraft, invoice finance, equipment finance or term loan is suitable for a planned cash flow gap.

The key is not to treat every unpaid invoice as business as usual. Owners should model repayments, stress-test slower debtor collection and check whether any proposed finance leaves enough buffer for tax, super and supplier obligations. A competitive rate is important, but structure, fees, repayment timing and security requirements can be just as influential.

Late payment culture is ultimately a fairness issue, but it is also a finance strategy issue. Small businesses cannot control every customer’s behaviour, yet they can set clearer boundaries and prepare funding plans that protect the business before cash flow becomes a crisis.

Published:Friday, 24th Jul 2026
Author: Paige Estritori

Please Note: We do not endorse any specific products or companies. Some content is sourced from third parties, including press releases, and may not be independently verified for accuracy or completeness.

Share this news item:

Rate this article

1 Comment

Z
Zain Cross 25 Jul 2026

Payday super is going to make 60-day payers even harder to carry, especially when GST and wages have already gone out.

Finance News

What tighter lending signals mean for new loan applications
15 Sep 2026: Paige Estritori
APRA’s latest banking indicators point to a lending market that is still open, but not loose. Mortgage credit continues to move through the system, yet the regulator’s focus on serviceability, risk controls and higher-risk lending means borrowers should expect applications to be examined carefully rather than waved through on headline income alone. - read more
What the latest growth data means for finance plans
08 Sep 2026: Paige Estritori
Australia’s latest national accounts have given borrowers a fresh read on the economy: growth is continuing, but momentum remains uneven and household spending is still being tested by higher living costs. For anyone weighing up a personal loan, home loan refinance, vehicle finance or business funding, the message is less about one headline number and more about how stable income, expenses and cash flow look over the next year. - read more
Why arrears data matters before your next finance decision
01 Sep 2026: Paige Estritori
Fresh lending and banking indicators are giving Australian borrowers a timely reminder: the headline interest rate is only one part of the finance decision. While some lenders have been adjusting selected offers and competition remains visible in parts of the market, arrears and repayment stress are still important signals for households and small to medium-sized businesses planning their next move. - read more


Finance Articles

An Insider's Guide to Enhancing Your Credit Profile for Any Loan
Having a robust credit profile is one of the most critical factors for financial health, especially when seeking loans in Australia. Whether you're eyeing a new car, dreaming of a home or simply want to secure a personal loan for unexpected expenses, your credit score often dictates the outcome. Not only does it influence a lender's decision to offer you finance, but it also affects the interest rates you might be charged. - read more
Top Mistakes to Avoid When Saving for Your First Home
Embarking on the journey to homeownership is both exciting and daunting. It's a significant milestone that requires careful planning and disciplined saving. For many Australians, buying a first home represents a dream come true, and it's essential to approach it strategically. - read more
How to Choose the Right Personal Loan in Australia
Personal loans can be used for a range of personal expenses, from debt consolidation and renovations to larger purchases or travel. Before applying, it is important to understand how different loan types, rates, fees and repayment terms affect the total cost and whether the repayments fit your budget. - read more

Personal Loan Repayment Calculator

Personal Loan Repayment Calculator

The Great Australian Side-Hustle

The Great Australian Side-Hustle

Finance Australia's Weekly Money and Business News

Finance Australia's Weekly Money and Business News

Stay informed with MoneyTips

Get practical financial information, news, guides and resources.


Knowledgebase
Conventional Loan:
A type of mortgage loan that is not insured or guaranteed by the government.