The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
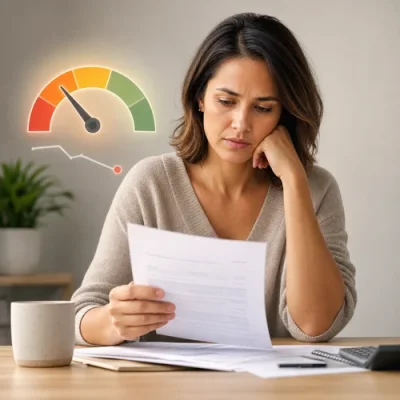
Your Credit Rating (or Credit Score) plays a very important role in determining your eligibility to get a loan. Here we look at the reasons why your credit score may drop and some handy tips to avoid this problem.
Your credit rating is very important. It is used to determine how much interest you need to pay. It is also a reflection of your creditworthiness.
If you have high credit rating, you can enjoy lower interest charges on loans. Apart from that, you also get higher credit limit and great deals on your credit card.
If you find that your rating has dropped significantly, this may mean that you may have made a financial mistake.
There are a number of reasons why you may suddenly have a lower score.
If you know what these reasons are, there is a chance that you can avoid or at least fix your current dilemma. Here are some possible causes of abrupt score drop and how you may be able to avoid them.
Late Payments
Your payments reflect 35% of your FICO score, regardless of whether you pay on time or not.
If you missed a payment, this will not completely damage your rating. However, if you turn this into a habit, your score will eventually be affected.
Moreover, your creditor may charge you with more fees and you may likely end up having to make many more payments, which could include your credit card bills, immediate fees for missed payments, and charges on credit lines and later, loans.
The only solution to avoid all these is to pay your bills on time.
New Credit Card Application
Applying for a new card when you are struggling with paying another can hurt your credit score. Know that 10% of your credit rating is made up of new inquiries for credit.
New card applications will show on your credit report for 12 months.
If you wish to get a new card, do so with control. If you are to make an inquiry, do it only once as much as possible.
Finance Australia's Weekly Money and Business News
 This week: inflation rose to 4.3% in September, keeping pressure on the RBA ahead of its Tuesday, 3 November meeting. Treasury proposed banking deregulation to boost competition, including lifting the covered bond cap and doubling the no‑probate estate payment limit. ASIC is consulting on guidance for the Scams Prevention Framework, with AFCA to take broader scam complaints from 31 March 2027. And SMEs are receiving ATO letters about possible super shortfalls; theyre prompts to check records, not automatic debts. Listeners are urged to stress‑test repayments, compare rates and fees, secure payments against scams, and keep payroll and super records in order. Visit finance‑australia.net for guides and calculators.
One inquiry is acceptable since your score can rebound within a year.
Credit Card Cancellation
You have the option to close your account if you have credit card debt.
However, doing so will actually damage your score, especially if your account carries a balance.
Another possible scenario is that creditors may cancel your account.
Both scenarios can have an effect on your rating; therefore, avoid credit card cancellation as much as possible.
Unemployment Benefits
If you are unemployed and you get benefits, this will have a slight effect on your score. It is advised that you receive the benefits for a short period only. Although the credit bureaus will not find out if you are unemployed, they will certainly see that your income has decreased.
High Credit to Debt Ratio
Your extended credit will take 30% of your credit score.
Sudden increase in balances without higher credit limit will result to a score drop.
If you have balances, strive to pay them off as soon as possible.
Poor Debt Management
Credit score is not only about what you do with your credit cards. There are other factors that can influence your score.
These include your lines of credit and loan balances, which comprise 30% of your FICO score.
If you have too much debt, your rating will definitely go down. It will also be difficult for you to afford the payments each month.
Hence, you should be able to manage your debt by lowering the amount of money you owe from various financial institutions.
Published: Wednesday, 18th Aug 2021
Author: 260




No comments yet. Be the first to share your thoughts.